Provident Fund, usually known as PF, is one of the most important social-security benefits for employees in India. For payroll professionals and employees, understanding PF is important because every month a portion of salary is contributed towards the employee’s PF account.
But many employees have questions like:
- What exactly is PF?
- How is employee PF contribution calculated?
- How much does the employer contribute?
- Is the entire employer contribution deposited into PF?
- How can I calculate my total PF contribution for the entire year?
- What is EPS?
- How much PF can I withdraw?
- Can I withdraw the employer contribution also?
In this article, we will understand PF with a simplesalary example and payroll calculation.
1. What is Provident Fund?
Provident Fund is a retirement-oriented social-security scheme for entitled employees. In the organised sector, PF is generally managed through EPFO — Employees’ Provident Fund Organisation.
Employee contributes → Employer contributes → Amount accumulates in the PF account → Interest is credited → Eligible amount can be withdrawn/transferred according to applicable rules.
PF can consequently help employees shape a long-term retirement corpus. in April 2026 lots of payroll changes introduced .
2. How Does PF Contribution Work?
For a typical EPF-covered employee, the contribution is calculated on PF wages, mainly Basic wages plus applicable Dearness Allowance, rather than automatically on the employee’s entire gross salary.
A commonly used contribution structure is:
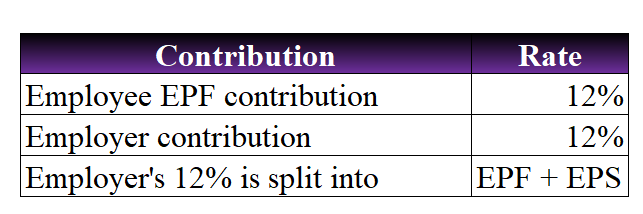
The significant point is that the employee’s entire 12% goes towards EPF, while the employer’s contribution is commonly divided between EPF and EPS, subject to the applicable rules and wage ceiling.
3. Employee PF Contribution Calculation
Let’s take a simple example. Suppose:
Basic Salary = ₹30,000 per month For illustration, assume PF wages are ₹30,000.
Employee PF: ₹30,000 × 12% = ₹3,600 Therefore:
Employee PF contribution = ₹3,600 per month
This amount is deducted from the employee’s salary and deposited towards PF. Annual Employee Contribution
₹3,600 × 12 = ₹43,200
So, based on this example, the employee contributes ₹43,200 in one year, before considering interest.
4. How is Employer PF Contribution Calculated?
The employer also contributes generally at 12% of PF wages. Using the same example:
PF wages = ₹30,000 Employer contribution:
₹30,000 × 12% = ₹3,600
But there is an important difference. The employer’s contribution is generally divided between:
- EPF
- EPS — Employees’ Pension Scheme
So, you should not simply assume that the entire employer contribution of ₹3,600 is added to your EPF balance.
5. What is EPS?
EPS stands for Employees’ Pension Scheme. A portion of the employer’s contribution is allocated towards EPS, subject to the applicable statutory provisions and wage ceiling.
For the standard wage-ceiling calculation, the EPS contribution is generally calculated at 8.33% of ₹15,000, which works out to:
₹15,000 × 8.33% = approximately ₹1,250 The remaining portion of the employer’s contribution goes towards EPF.
Therefore, where the statutory ₹15,000 wage ceiling applies: Employer contribution = ₹1,800
Out of this, approximately:
- EPS = ₹1,250
- Employer EPF = ₹550
So the PF account does not necessarily receive the full employer’s ₹1,800 as EPF.
Important: Actual contribution action can vary depending on the employee’s EPF/EPS membership, applicable wage ceiling, establishment coverage and other statutory conditions. Payroll calculations should therefore be checked against the applicable EPFO rules.
6. Example: Complete Monthly PF Calculation
Let’s understand it with a practical payroll example.
Employee Salary
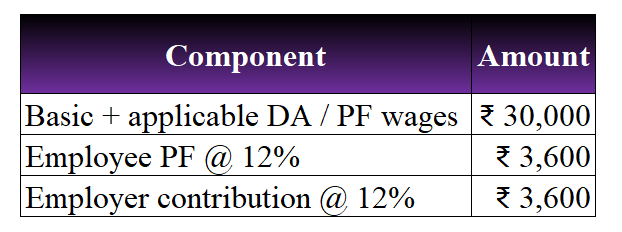
Assuming the standard EPS wage ceiling applies:
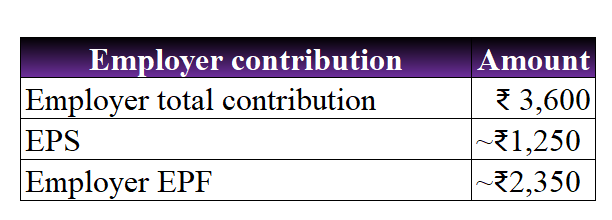
Therefore: Employee EPF = ₹3,600
Employer EPF = ~₹2,350
EPS = ~₹1,250
Total monthly amount going toward EPF + EPS = ₹7,200 But the EPF balance would increase by approximately:
₹3,600 + ₹2,350 = ₹5,950 per month
before interest.
7. How to Calculate Your Entire PF Contribution for the Year?
This is where many employees get confused. Assume your monthly employee contribution is:
₹3,600
and employer EPF contribution is approximately:
₹2,350
Then:
Employee contribution for 12 months
₹3,600 × 12 = ₹43,200
Employer EPF contribution for 12 months
₹2,350 × 12 = ₹28,200
Therefore, approximate EPF principal contribution:
₹43,200 + ₹28,200 = ₹71,400
This is before PF interest.
EPS contribution is tracked separately and should not simply be added to the EPF balance.
8. What About PF Interest?
PF is not just about the contributions. Interest is also credited to the EPF balance at the applicable annual rate declared by the government/EPFO.
Therefore:
Final PF balance ≠ Employee contribution + Employer contribution only
Instead:
PF Balance = Employee EPF + Employer EPF + Interest + Previous PF balance, if any
Also remember that PF interest is calculated giving to the applicable EPFO methodology, so basically multiplying the annual contribution by the annual interest rate may not give the exact passbook amount.
9. How Can I Calculate My Total PF From My Salary?
If you want to calculate your PF contribution for your entire employment period, create a simple Excel sheet.
For example:
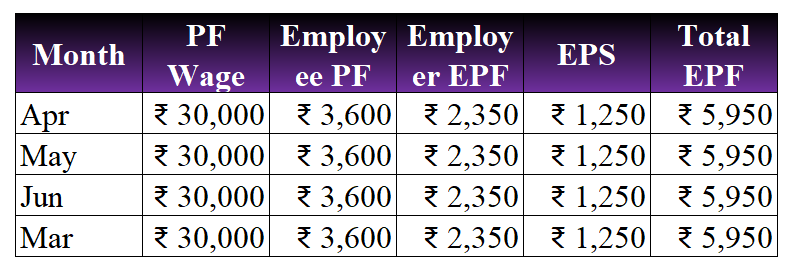
Then calculate:
Employee PF = SUM(Employee PF column)
Employer EPF = SUM(Employer EPF column)
Total EPF contribution = Employee PF + Employer EPF
And finally add the applicable interest.
10. Where Can I Check My Actual PF Contribution?
The best way to verify your actual PF contribution is to check your EPFO passbook.
Your passbook can help you see the contribution credited by:
- Employee
- Employer
- EPS
- Interest, where applicable
This is more reliable than calculating only from your CTC or salary slip because your actual PF contribution may be affected by the applicable wage ceiling, contribution structure, joining/exit dates, wage changes, etc.
11. Can I Withdraw the Employer Contribution?
Yes, subject to the applicable EPFO withdrawal rules, eligible EPF accumulations can include both employee and employer EPF contributions.
However, remember the distinction:
Employee EPF
Your contribution goes into EPF.
Employer EPF
The EPF portion of the employer contribution goes into EPF.
EPS
The pension contribution is treated separately and withdrawal/benefit rules are different.
Therefore, don’t calculate your withdrawal amount simply as:
Employee contribution × 2
You need to consider:
Employee EPF + Employer EPF + applicable interest
and the applicable withdrawal/benefit rules.
12. How Much PF Can I Withdraw?
The amount you can withdraw depends on why you are withdrawing and your eligibility under the applicable EPFO rules.
PF withdrawal is not always simply “withdraw 100% whenever you want.”
Different provisions may apply for:
- Final settlement after leaving employment
- Unemployment
- Medical treatment
- Education
- Marriage
- Housing
- Other permitted purposes
The allowed amount and conditions can vary depending on the withdrawal category and current EPFO rules.
Consequently, before applying for a withdrawal, always check the latest EPFO provisions applicable to your case.
13. PF Withdrawal vs PF Transfer
If you change your job, you don’t essentially need to withdraw your PF.
If you join another PF-covered employer, transferring your existing PF balance to the new member account/UAN-linked account can generally be desirable for maintaining continuity.
For example:
Company A → Company B → Company C
Instead of withdrawing PF every time you change jobs, your PF can continue gathering under the applicable UAN/member-account structure.
This can help preserve your retirement savings and service continuity.
14. Common PF Calculation Mistakes
Mistake 1: Calculating 12% on Gross Salary
PF is not automatically 12% of gross salary.
You need to identify the applicable PF wages.
Mistake 2: Adding the Entire Employer Contribution to EPF
Employer contribution includes the portion allocated towards EPS where applicable.
Mistake 3: Ignoring the Wage Ceiling
The statutory wage ceiling can affect the calculation, subject to the employee’s conditions and applicable rules.
Mistake 4: Ignoring EPS
EPS is separate from the EPF balance.
Mistake 5: Calculating Interest on Annual Contribution Directly
PF interest calculation is not as simple as:
Annual contribution × annual interest rate
The applicable calculation procedure needs to be considered.
15. Simple PF Formula
For a standard illustration:
Employee Contribution
PF Wage × 12%
Employer Contribution
PF Wage × 12%
Employer EPF
Employer contribution − EPS contribution
Total EPF Principal
Employee EPF + Employer EPF
Final EPF Balance
Previous balance + Employee EPF + Employer EPF + applicable interest
16. Important Point for Payroll Professionals
If you are working in payroll, don’t calculate PF only from the employee’s salary structure.
You should check:
- PF wage
- Employee PF rate
- Employer contribution
- EPS applicability
- Wage ceiling
- Employee’s EPF/EPS membership status
- Contribution days
- Joining and exit dates
- Arrears
- Applicable statutory rules
This becomes particularly important during new joiners, exits, salary revisions, arrears and full & final settlement.
About the Author
